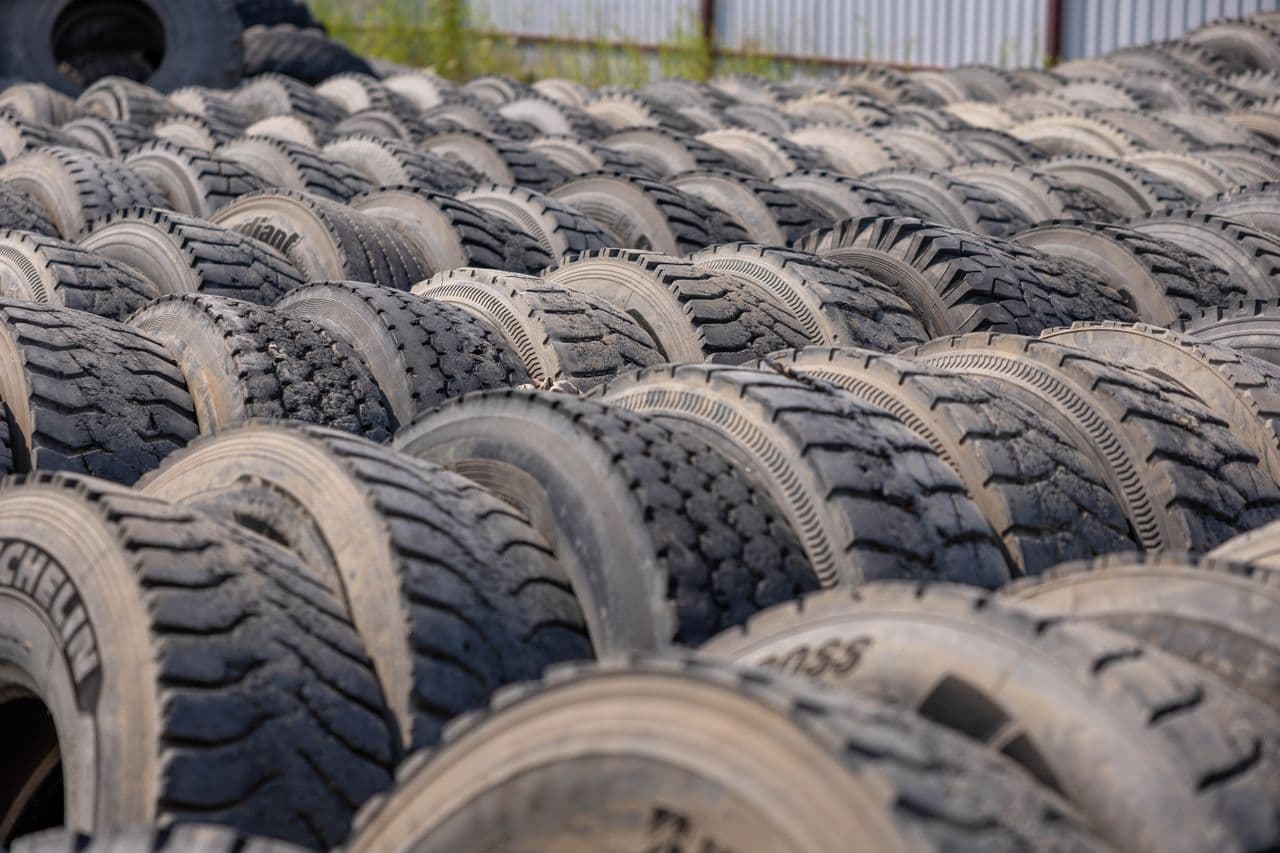
Prevent scrap at source to decarbonise tyre production
 Brisa
 SKD Türkiye
总结
Quality losses in tyre production are prevented at source through structured problem solving, cutting carbon, water, energy and raw material use in one programme.
Context
Submitted through the COP31 Sustainable Transformation Awards · SKD Türkiye (WBCSD Global Network Partner)
The company manufactures tyres in Türkiye and employs more than 1,000 people.
Tyre production is resource intensive. Every unit consumes natural rubber and other raw materials, process energy and large volumes of water, and a unit that fails quality inspection carries the full environmental burden of all of it. The material is lost, the energy has already been spent and the water has already been used, but no product reaches a customer.
Manufacturing improvement work has traditionally treated that loss as a cost and quality problem, measured in scrap value and yield. Measured that way, the environmental consequence stays invisible, and improvement projects compete against each other for attention instead of accumulating.
The company's response was to reframe the problem. Quality losses were redefined as losses of carbon, energy, water and natural resources as well as of money, so that the environmental gain from preventing a defect could be quantified and could justify the improvement effort on its own terms.
The initiative was launched in 2025, which is also the baseline year against which performance after implementation is compared. It began with pilot applications and, after the results were confirmed, was extended to other production areas as a company-wide model.
Location of the initiative: Türkiye
Solution
The approach is captured in a single operating principle: make the product right the first time, so that the resources embedded in a defective unit are never consumed at all. Losses are prevented at source rather than managed after they have occurred, which is what connects the work to circular economy thinking rather than to waste handling.
Two design choices distinguish it from conventional manufacturing improvement.
The first is the measurement frame. Scrap reduction, process development, capacity increase and quality improvement work are each evaluated in five currencies at once: carbon emissions, natural rubber consumption, energy use, water use and financial benefit. A change that improves yield is therefore reported as an emissions result and a water result, not only as a cost result.
The second is the basket. Improvement activities that appear unrelated — a scrap reduction study on one line, a process adjustment on another, a capacity change elsewhere — are grouped into a single basket project and managed against shared sustainability targets. That grouping is what converts local gains into system-level improvement, because it forces the portfolio to be assessed as a whole rather than project by project.
Standard management tools carry the work: A3 problem solving, plan-do-check-act cycles, the define-measure-analyse-improve-control method and cross-functional teams drawn from the functions that own the process. No major capital investment or new technology was required; the initiative uses the existing workforce, the existing data infrastructure and established problem-solving methods.
Environmental effects are quantified against defined references. Carbon calculations follow the GHG Protocol approach, and the environmental effects of the improvements in natural rubber, energy and water consumption are derived from sector references and unit consumption data published by the Japan Automobile Tyre Manufacturers Association, so the figures rest on an industry method rather than on internal assumptions.
Impact
Sustainability Impact
Climate
The initiative reduces emissions by preventing production that would have been scrapped. A rejected unit carries the full energy and material burden of the process that made it, so preventing the defect prevents that burden entirely rather than recovering part of it afterwards.
Carbon calculations follow the GHG Protocol approach, using production data, raw material consumption records and energy and water use records. Against the 2025 baseline, the initiative prevented 11,000 tonnes of carbon emissions and avoided 2,901 MWh of energy consumption.
The avoided energy is site energy, so it reduces the plant's own Scope 1 fuel consumption and its Scope 2 purchased electricity directly. The avoided natural rubber reduces the upstream burden carried in the value chain rather than emissions at the plant.
Performance is tracked through prevented carbon emissions, prevented natural rubber consumption, energy consumption, water consumption and sustainable economic benefit, which keeps the climate result inside the same reporting set as the operational one.
Nature
Preventing 369 tonnes of natural rubber consumption reduces pressure on natural resources at the point where tyre manufacturing has its largest land-related footprint. Natural rubber production carries land use and biodiversity consequences in the growing regions, so material not consumed is cultivation not required, and the effect is felt upstream rather than at the plant.
Water is the second nature-related result. The initiative saved 7 billion litres of water, which is abstraction avoided rather than water treated and returned, and it is the outcome with the most direct local relevance for a manufacturing site.
Social
The most durable internal effect is a change in how resource use is understood. Employees who previously assessed a defect in terms of cost and rework now see it expressed in carbon, water, energy and raw material terms, and that reframing has altered how improvement opportunities are identified and prioritised.
Cross-functional working has become routine rather than exceptional. Sustainability, technology, production, quality, engineering and operations teams work on the same problem definitions and share the same performance indicators, which has strengthened collaboration between functions that previously optimised separately.
Business Impact
Benefits
The financial result is TRY 38 million of sustainable economic benefit a year, achieved without major capital investment or new technology, which makes the return a function of how the existing workforce and data are used rather than of a spending decision.
Waste in production falls and resource efficiency rises across the improvement portfolio, and the capacity released by producing fewer defective units is available for saleable output rather than for rework.
Because the same improvement is reported in carbon, rubber, energy, water and financial terms, a single project satisfies several objectives at once, which improves the return on the engineering and quality resource committed to it.
The results have been standardised and transferred to other production areas, so the benefit compounds as the model spreads rather than remaining confined to the lines where it started.
Beyond the direct saving, sustainability-focused problem solving has become part of how the organisation works, which lowers the cost of identifying the next set of improvements.
Costs
The initiative required no major investment and no new technology, so its cost is measured in capability rather than in capital: the time of engineers, quality specialists and production teams working through A3 problem-solving studies, the analytical effort of converting production and consumption data into environmental terms, and the training needed for the plan-do-check-act and define-measure-analyse-improve-control methods to be applied consistently.
The real constraint is skilled attention. Cross-functional teams working on improvement studies are not available for other work, and an organisation without spare engineering and quality capacity will have to create it before this model produces results.
There is a dependency on data quality. The environmental result rests on production data, raw material consumption records and energy and water use records being accurate at the level of the individual process, and a plant whose metering is aggregated at site level cannot attribute improvements to particular changes.
Costs are contained by using established methods rather than developing new ones, by grouping related studies into a basket so that the analytical work is done once for several projects, and by standardising and transferring proven solutions instead of solving the same problem again in each production area.
Impact Beyond Sustainability and Business
Co-benefits
The saving of 7 billion litres of water has value beyond the emissions result, particularly for manufacturing sites in regions where water availability constrains operations.
The model is not tied to a production line, a plant or an industry. Because it rests on data-driven problem solving, cross-functional collaboration and continuous improvement, it transfers to automotive, rubber, plastics, chemicals and other resource-intensive sectors without adaptation of the underlying method.
The value chain benefits indirectly. Optimising raw material use reduces the volume a supplier has to produce and deliver, so suppliers are treated as indirect stakeholders in the result rather than as parties outside it.
The basket project structure is itself transferable. Grouping unrelated improvement work under shared sustainability targets is a management technique that any manufacturer can adopt regardless of what it produces.
Potential Side-Effects
Reporting the same improvement in five currencies risks double counting if the boundaries are not fixed. A change that reduces both scrap and energy can be claimed twice unless each study defines what is attributed to it, which is why the basket has to be assessed as a whole rather than as a sum of individually reported projects.
A baseline set in the same year as launch, as here with 2025, gives a short comparison period. The result reflects the difference before and after implementation rather than a multi-year trend, and a longer series will be needed before the improvement can be separated from normal year-to-year variation.
Loss prevention has a natural limit. The easiest defects are removed first, so the rate of improvement will fall in later cycles and an organisation planning on a constant rate of return will be disappointed.
Freed capacity is a benefit only if there is demand for it. Preventing defects releases production capacity, and in a market without additional demand that shows up as lower utilisation rather than as additional output.
Implementation
Typical Business Profile
The model suits resource-intensive manufacturers whose production losses carry significant embedded energy, water and raw material — automotive, rubber, plastics, chemicals and comparable process industries — and where quality rejection occurs late enough in the process that most of the resource has already been consumed.
It is most relevant to organisations that already have a structured problem-solving culture and production data at process level, since the method depends on both. Companies without them can still adopt it, but the first cycle will be spent building the data and the discipline rather than delivering savings.
Delivery engages sustainability, technology, production, quality, engineering and operations functions under joint ownership, with process owners and project teams coordinating the individual studies.
Approach
Redefine quality loss as resource loss: State explicitly that a defective unit represents carbon, energy, water and raw material already consumed, and require every improvement study to report those quantities alongside its financial result.
Fix a baseline and a conversion method before starting: Set the comparison year, and establish how production and consumption data will be converted into environmental terms — here the GHG Protocol approach for carbon and published sector references and unit consumption data for rubber, energy and water.
Group related studies into a basket: Bring scrap reduction, process development, capacity and quality improvement work together under shared sustainability targets, so that the portfolio is managed for system-level effect instead of as competing local projects.
Apply one standard problem-solving method: Use A3 problem solving supported by plan-do-check-act and define-measure-analyse-improve-control cycles across every study, so that results from different areas are comparable and can be aggregated.
Staff each study across functions: Build teams from sustainability, technology, production, quality and engineering, because the causes of resource loss usually sit across the boundaries that separate those functions.
Decide from production data rather than opinion: Base problem definition and prioritisation on production records, process analysis and shop-floor observation, and use regular operations meetings to review both the environmental and the operational effect together.
Quantify every improvement in all five currencies: Report prevented carbon emissions, prevented raw material consumption, energy consumption, water consumption and economic benefit for each study, so that the environmental case does not depend on the financial one.
Standardise what works and transfer it: Convert successful applications into standards and deploy them to other production areas, which is how local gains become a company-wide result.
Extend the logic upstream: Treat suppliers as indirect stakeholders and use optimised raw material consumption as the route to reduce environmental impact along the value chain.
Stakeholders Involved
Project leads: The initiative is jointly owned by the sustainability, technology, production, quality and engineering functions rather than assigned to one of them, which is what allows resource efficiency and low-carbon production targets to be managed under a shared understanding of performance.
Process owners and project teams coordinate the individual studies. Performance is monitored against defined indicators and reviewed in management processes on a data basis, so that corrective action can be taken quickly rather than at the end of a reporting cycle.
Permanence was designed in: standard management tools are embedded in daily operations and employee participation is actively encouraged, so the work is part of how the company operates rather than a project with an end date.
Company functions: Sustainability, technology, production, quality, engineering and operations teams participate together. The knowledge and field experience of the different disciplines is brought onto one platform to establish the causes of resource loss and to surface improvement opportunities that a single function would not identify.
Participation runs through A3 problem-solving studies, shop-floor observation, regular operations meetings and performance review processes. The feedback generated in those forums is used to prioritise improvement actions and to develop the applications further, so the mechanism is continuous rather than periodic.
Decisions are shaped by production data, process analysis and the joint assessment of the teams, with environmental and operational effects considered together rather than in separate reviews.
Main providers: No external solution provider led the work. The initiative was delivered with the existing workforce, the existing data infrastructure and established problem-solving methods, which is a significant part of why it is replicable by companies without a technology budget.
Published sector references and unit consumption data from the tyre manufacturers' industry association were used as the external methodological basis for quantifying the natural rubber, energy and water effects.
Other: Suppliers were treated as indirect stakeholders. Optimising raw material use and raising resource efficiency reduces the volume that has to be produced upstream, so the sustainability effect extends along the value chain without a separate supplier programme.
Successful applications are standardised and shared internally so that other production areas adopt them directly, which is the mechanism through which the model scales.
Key Parameters to Consider
The baseline year is 2025, which is also the launch year, so results are stated as before-and-after comparisons rather than as a multi-year trend.
Environmental effects are calculated from production data, raw material consumption records and energy and water use records. Carbon follows the GHG Protocol approach; natural rubber, energy and water effects use published sector references and unit consumption data from the Japan Automobile Tyre Manufacturers Association.
The indicator set is fixed at five measures: prevented carbon emissions, prevented natural rubber consumption, energy consumption, water consumption and sustainable economic benefit.
Maturity requirements are a working problem-solving culture, process-level production data and available engineering and quality capacity. The method itself — A3, plan-do-check-act and define-measure-analyse-improve-control — is standard and does not have to be developed.
There is no technology dependency and no minimum investment threshold, which means the model can be started at the scale of a single production line and expanded from there.
Implementation and Operations Tips
Convert the loss into environmental units before starting the improvement work, not afterwards. If the conversion method is agreed first, every study reports its environmental result automatically and the figures are consistent; retrofitting the calculation to completed projects produces numbers nobody trusts.
Group the studies. Individually, a scrap reduction on one line is too small to attract management attention; grouped into a basket with shared targets, the same work becomes a programme with a visible result.
Use methods people already know. A3, plan-do-check-act and define-measure-analyse-improve-control were chosen because the workforce could apply them immediately, which meant the effort went into solving problems rather than into learning a new system.
Put the environmental and financial results in the same report. Presenting TRY 38 million alongside 11,000 tonnes of carbon and 7 billion litres of water is what keeps both audiences engaged in the same improvement portfolio.
Standardise before spreading. Transferring an unstandardised improvement produces variable results in the receiving area and undermines confidence in the model, so documentation should precede deployment.